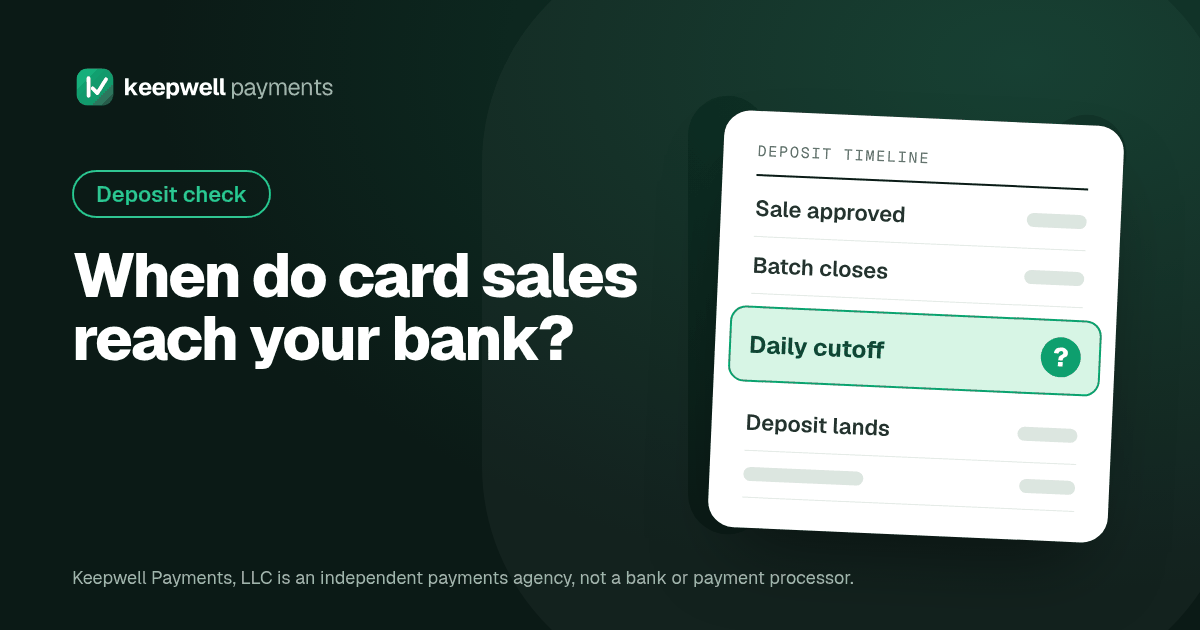
A busy day of card sales, and the money isn't in your bank account yet. That's normal. A card sale goes through a few steps before it becomes a deposit, and each step can add time. Here's how it works, and what to ask your provider.
What happens between a card sale and your deposit?
When a customer pays, the card is approved right away. But the money hasn't moved yet.
- The sale is approved. The approval says the card can cover the sale. No money has reached you.
- Sales collect in a batch. Your approved sales for the day are grouped together.
- The batch closes. When the batch closes, it gets sent off for payment. Some terminals close the batch automatically, at a set time each day. Ask how yours works.
- The deposit lands. The money for that batch is sent to your business bank account.
What is a daily cutoff time?
Your processor also has a daily cutoff time. Close your batch before the cutoff, and it goes out with that day's payments. Close it after, and it can take a day longer.
When the money lands depends on your provider, so ask, or check your agreement. Ask what time the cutoff is and which time zone it uses.
Do weekends and bank holidays change when money arrives?
They can. Deposits move on business days. A Friday night batch may not land until Monday, and bank holidays can add a day. If a deposit seems late after a long weekend, count business days, not calendar days.
Why is a deposit smaller than your card sales?
If a deposit looks smaller than your sales, check how your fees are taken. Some processors take fees out of each deposit. Others bill them once a month. Your provider can tell you which way your account works.
Other things can change a deposit too. Refunds you issue may come out of what's deposited. If a customer disputes a charge and the dispute moves forward, the disputed amount is taken back from you while it's reviewed. Our guide to what to do in the first 24 hours of a chargeback covers that process.
How do you match a deposit to your sales?
Match each deposit to its batch report, so nothing slips. A simple log helps: the batch date, the batch total, the deposit date and the deposit amount. If a deposit doesn't match, the difference can point to fees, refunds or a dispute.
Your monthly processing statement shows the fees behind those differences. Our guide to reading your processing statement shows where to find them.
Can you get deposits sooner?
Know your cutoff time, and close your batch every day. Then ask your provider whether faster deposits are offered, and what they cost. Get the answer in writing, so you know the timing and any added fee before you choose.
What should you ask your provider?
- What is my daily cutoff time, and in which time zone?
- Does my terminal close the batch automatically? At what time?
- After a batch closes, how long until the deposit lands?
- Are fees taken out of each deposit, or billed once a month?
- Are faster deposits offered, and what do they cost?
- Which report matches each deposit to its batch?
If you're comparing providers, see Before You Sign: 9 Questions to Ask Any Merchant Services Provider for more.
Frequently asked questions
Why isn't my card money in my account yet?
A card sale is approved right away, but the money hasn't moved yet. Sales collect in a batch, the batch closes and is sent for payment, and then the deposit lands. The daily cutoff time and business days can add time.
What is a batch cutoff time?
It's the time of day your processor uses to decide which day a closed batch goes out with. Close your batch before the cutoff. Close it after, and it can take a day longer. Ask your provider for your cutoff time.
Do deposits arrive on weekends?
Deposits move on business days. A Friday night batch may not land until Monday, and bank holidays can add a day. Ask your provider how weekends and holidays affect your deposits.
Why is my deposit less than my card sales?
Some processors take fees out of each deposit. Others bill them once a month. Refunds and disputed charges can also change a deposit. Match each deposit to its batch report to see the difference.
Can I get my card deposits faster?
Know your cutoff time and close your batch every day. Then ask your provider whether faster deposits are offered, and what they cost. Get the answer in writing before you choose.
How we approach it at Keepwell
Not sure what you're paying, or when you're getting paid? Send us one month's statement for a free review. We'll walk you through your fees and your deposits, in plain English.
Want us to look at your statement? Upload it at keepwellpayments.com/upload for a free, no-obligation review.
Keepwell Payments, LLC is an independent payments agency, not a bank or payment processor. Each merchant account is set up with a payment processor we partner with and its sponsor bank, named in writing before you sign. Merchant accounts are subject to approval. Results vary by business. This article is general information, not financial advice.